Persistent raised ₹11,865 crore in 11 days for Nagarro; 64% of it is debt at about 9%
How Persistent Systems is paying for Germany’s Nagarro: the share sale, debentures and commercial paper of 26 October to 5 November, what they cost, and what is still open.

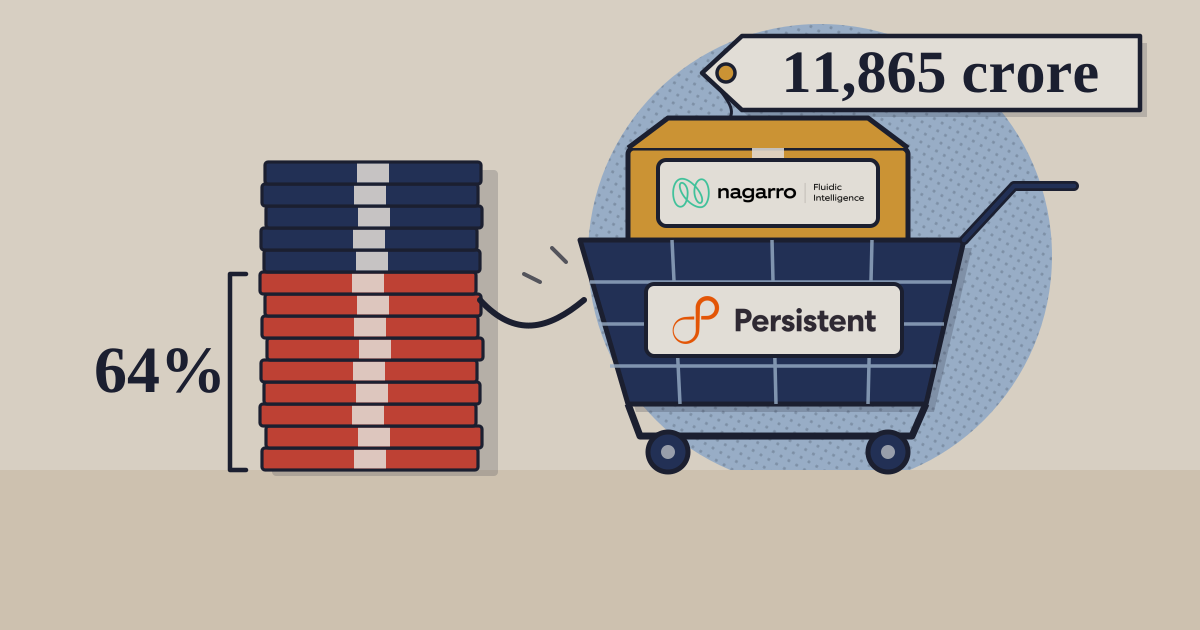
Persistent Systems allotted ₹11,865 crore of new securities in the 11 days to 5 November: ₹7,000 crore of debentures at 8.95%, shares worth ₹4,264.6 crore and ₹600 crore of commercial paper at 8.75%.123 All of it is for one purchase, Nagarro SE of Munich, for which Persistent announced an offer of €81 a share in cash in June and has since secured 94.04%.4514 The sum is about 2.5 times the ₹4,664 crore of revenue Persistent earned last quarter and, at NSDL’s ₹95.25 to the dollar on 2 November, about US$1.25bn, the limit its shareholders approved on 5 October.6812
01What it raised, and why at the parent
The money replaces a stopgap. Persistent arranged a bridge loan of up to €1.4bn for 18 months; in September it told shareholders it must be replaced with long-term financing, up to US$1,250m in all, of which no more than US$450m in equity.7 It raised it at the parent for a stated reason: it has promised not to sign a domination agreement with Nagarro for two years, so it “will have limited access to the cash-flows of Nagarro during that period”. Nagarro’s own revolving credit, about €290m drawn, stays with Nagarro.7
Of the debentures, ₹4,500 crore are backed by a pledge over Nagarro’s shares and the account holding the proceeds; ₹2,500 crore are unsecured.2 The share sale added 76.8 lakh shares at ₹5,550, 3.66% below the ₹5,761 floor price, lifting the share count by 4.9%.1
02What it costs
On 15 October the finance chief, Vinit Teredesai, told analysts to assume a cost of “between 5 to 6% on a net basis”, before the debt was raised.8 He did not define net. After tax at the quarter’s 22.5% rate, 8.95% is about 6.9%, by our arithmetic. The debt is in rupees and the price is in euros; the filings we read do not say whether that is hedged.
The deal has already reached the profit line. Net profit fell 27.2% from the previous quarter to ₹351.5 crore; operating profit after tax, which leaves out ₹185.34 crore of Nagarro costs (₹143.6 crore after tax, by our arithmetic), rose 2.5% to ₹495.2 crore.68 Those costs (advisers, bridge commitment fees, lawyers, regulatory filings) are expected to reach about US$50m in all over three to four quarters.8
03What is still open
The tendered shares have not yet been paid for. Persistent has secured 94.04% through a purchase agreement with Lantano Beteiligungen (22.10%) and two tender periods (61.15% and 10.79%), and settlement waits on the remaining offer conditions.5 On 15 October those were merger or investment clearances in Austria and Spain and the Reserve Bank of India’s approval.8 It expects to close by the end of March 2027, and intends to squeeze out the remaining holders and delist Nagarro from Frankfurt.89
Persistent has published no total for the offer. At €81 for about 1.24 crore shares, by the filed tender percentages, the equity comes to about €1.0bn.54 Crisil rates the debentures AA+ on “Rating Watch with Developing Implications”; ICRA rates them AA+ on “Rating Watch with Negative Implications” and the commercial paper A1+.1011 Those watches, and the first quarter that carries the interest, are the next numbers to read.
Sources
- Persistent Systems, allotment of equity shares under the QIP — 26 October 2026 Issue closure: separate filing the same day.
- Persistent Systems, allotment of non-convertible debentures — 4 November 2026
- Persistent Systems, allotment of commercial paper — 5 November 2026
- Persistent and Nagarro sign Business Combination Agreement (press release) — 26 June 2026
- Persistent Systems, update on the voluntary public takeover offer for Nagarro SE — 9 October 2026
- Persistent Systems, press release on Q2 FY27 results — 15 October 2026
- Persistent Systems, notice of Extraordinary General Meeting (held 5 October 2026) — 12 September 2026
- Persistent Systems, transcript of the Q2 FY27 earnings call — filed 23 October 2026 Call of 15 October 2026.
- Persistent's Takeover Offer for Nagarro Successful (filed with NSE) — 22 September 2026
- Persistent Systems, credit rating intimation (Crisil, non-convertible debentures) — 21 October 2026
- Persistent Systems, credit rating intimation (ICRA) — 22 October 2026
- NSDL, Daily Trends in FPI Investments, November 2026 (conversion rate for 2 November) — 2 November 2026
- Persistent Systems, outcome of board meeting: audited results for the quarter to 30 September 2026 — 15 October 2026
- Persistent Systems, Special Committee outcome: terms of the debentures and commercial paper for the Nagarro acquisition — 16 October 2026
Disclosure. TechBag is a software reseller: it earns a margin when a reader buys through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading