Markets & the AI economyAnalysis
PTC lost a US$228 bid to a press leak; Schneider is paying US$205
What PTC’s merger proxy of 13 November shows: a US$228 offer that ended in July 2025, three Schneider bids in 11 days, US$205 “best and final”, and a 17 December vote.

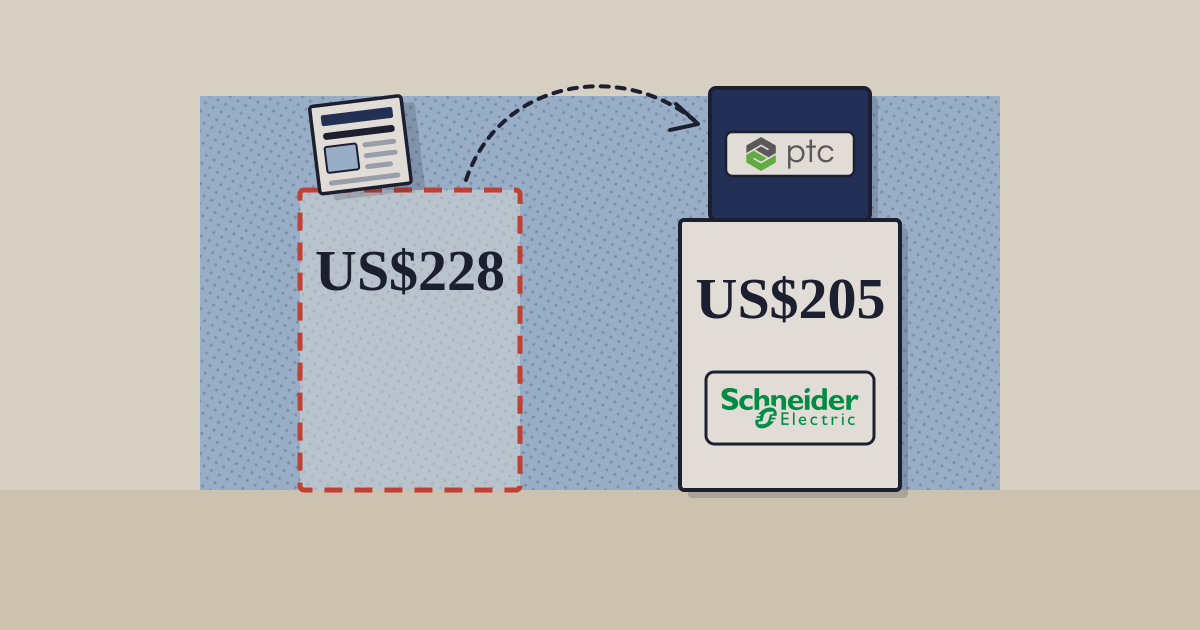
PTC, based in Boston, sells the software manufacturers use to design products and manage the data about them: Creo for 3D computer-aided design (CAD), Windchill for product lifecycle management (PLM), and Onshape, which runs CAD and data management in the cloud.4 On 5 October it and Schneider Electric, the French energy-technology group, announced that Schneider would buy PTC for US$205 a share in cash, 42.3% above the US$144.03 close of 2 October.2 The proxy PTC filed on 13 November, the document its shareholders vote on, tells how that price was reached. It answers a question the announcement did not: why a company that had a US$228 offer on the table in 2025 is selling for less, and who set the US$205.1
01US$228, a data room, and an article
The first approach came from “Company X”, the only name the proxy gives it. In April 2025 its chief executive told Neil Barua, PTC’s chief executive, that Company X was interested in a combination. PTC’s board decided on 20 May not to negotiate without a formal proposal, and asked Evercore to advise it. Company X sent one on 10 June 2025, signed a confidentiality agreement with a standstill that ran until 14 June 2026, and on 2 July raised its offer to US$228 a share, “a mix of cash and shares of Company X stock”. PTC opened its data room to it.1
A week later the talks were over. “On July 9, 2025, after the publication of an article speculating about a potential strategic transaction involving PTC, Company X terminated discussions,” the proxy says, and both sides returned or destroyed the information they had exchanged.1 PTC had closed at US$173.31 on 2 July, so US$228 was 31.6% above that day’s price; on 9 July the shares closed 17.6% higher, at US$210.47, according to Nasdaq.com.5 Two days earlier PTC had turned down Schneider’s first idea, a stake bought with cash and Schneider software assets that would have left PTC listed, as “overly complex”.1
The proxy does not say how much of the US$228 was cash, so what the offer was worth would have moved with Company X’s own share price. On the share count behind Schneider’s US$22.6bn, US$23 a share comes to about US$2.5bn.12
02What changed in between: the price of software
PTC went back to its own plan, and the market moved under it. The proxy describes what followed in one paragraph:
Over the end of 2025 and the beginning of 2026, market concerns regarding the impact of AI on SaaS businesses contributed to increased volatility and valuation compression … Although PTC continued to report operating performance in line with expectations and increased its full-year ARR, revenue and earnings guidance during this period, PTC’s trading price and valuation multiples declined materially from August 2025.
From July 2025 the shares’ highest close was US$216.53, on 27 August 2025, and their lowest US$112.33 on 23 June 2026, 48% lower; Evercore’s own figures put the closing range in the year to 2 October 2026 at US$112 to US$206.15 The business did not shrink with them. Annual run rate (ARR), the yearly value of active subscriptions, was US$2,508m on 30 September 2026, up 8% on the year once two divested products are excluded, and revenue for the year was US$2,733m against US$2,739m.3
By August 2026 Barua was telling a suitor that PTC faced “headwinds in the marketplace as a result of the broad dislocation in software stock prices”, and the board’s list of reasons for selling names “the potential impact of AI and technological changes on SaaS businesses” and “current trends in trading prices and valuations of companies in the Company’s industry”.1 The Journal measured the first half of that slide across the sector in Software shed about US$1tn in a week.
03Three offers in 11 days, to a number the board chose
The 2026 process had two bidders. “Company Y”, which the proxy describes only as another large software company listed outside the US, offered US$180 to US$190 on 31 August: US$117 to US$123.50 in cash and the rest in American depositary receipts (ADRs) it had yet to list, which it expected by late spring 2027. It wanted six weeks of exclusive talks. Schneider offered US$190 in cash on 8 September, with no financing condition.1
On 9 September the board rejected both prices but offered each bidder confidential figures to show “value above their current offers”. It decided against a wide search for other buyers, citing the risk “that a premature leak could result in Schneider and Company Y terminating discussions, as had happened in 2025 with Company X”. Evercore said that, despite the 2025 talks with Company X, only one party met the board’s test, “Company Z”, and it declined the next day, “citing other strategic priorities”.1
Schneider raised its offer twice in 11 days and stopped at the US$205 the board had asked for
PTC's sale process from Company Y's proposal to the announcement, 31 August to 5 October 2026
Show tableHide table
| Date | Event | Detail |
|---|---|---|
| 31 Aug 2026 | Company Y: US$180–190 | Cash plus ADRs; asks for six weeks of exclusive talks |
| 8 Sept 2026 | Schneider: US$190 cash | No financing condition |
| 10 Sept 2026 | Company Z declines | The board rejected both offers on 9 September |
| 17 Sept 2026 | Schneider: US$200 | Wants to sign within two weeks |
| 18 Sept 2026 | Board sets a US$205 target | Barua told to negotiate for it |
| 19 Sept 2026 | Schneider: US$205, best and final | Draft merger agreement sent the same day |
| 4 Oct 2026 | Merger agreement signed | US$700m fee if PTC walks away for another offer |
| 5 Oct 2026 | Deal announced | PTC closes at US$192.26, up 33.5% |
Source: PTC merger proxy, Background of the Merger (13 Nov 2026); Nasdaq.com (5 Oct 2026 close, not a primary source) · as of 13 November 2026
Schneider moved to US$200 on 17 September. The next day the board told Barua to negotiate “with the goal of obtaining an offer price equal to $205 per share”, and on 19 September Schneider offered exactly that, which its chief executive, Olivier Blum, called its “best and final offer”. Company Y kept asking for exclusivity, PTC kept refusing, and after 30 September the two did not speak again.1 The agreement was signed on 4 October; that afternoon the Financial Times reported that Schneider was close to a deal, and the companies announced it the next morning.1 PTC closed at US$192.26 on 5 October, up 33.5%, on 29.6m shares traded against 1.1m on 2 October.5
04What Evercore's numbers said about US$205
Evercore, PTC’s adviser, told the board on 4 October that US$205 was fair, from a financial point of view, to PTC’s shareholders. The proxy sets out the analyses behind that opinion, each a range of value per share, using market data to 2 October and the forecasts PTC’s management gave Schneider and Evercore: ARR of US$2,783m at the end of the year to September 2027, rising to US$3,415m two years later.1
US$205 sat above four of Evercore's seven value ranges and inside the other three
Implied value per PTC share, low to high, by Evercore analysis, US$, market data to 2 October 2026
- Low
- High
Show tableHide table
| Low | High | Change | |
|---|---|---|---|
| Discounted cash flow | 160 | 210 | 31% |
| Peers, cash-flow multiple | 135 | 191 | 41% |
| Peers, earnings multiple | 137 | 189 | 38% |
| Takeover premiums, 20–40% | 173 | 202 | 17% |
| Future price, discounted | 186 | 201 | 8% |
| Past deals, value to ARR | 159 | 228 | 43% |
| Past deals, value to profit | 169 | 260 | 54% |
| Analysts' price targets | 140 | 230 | 64% |
| Closing prices, past year | 112 | 206 | 84% |
Source: PTC merger proxy, Opinion of Evercore Group L.L.C. (13 Nov 2026) · as of 13 November 2026 · The last two rows Evercore gives for reference only; the % is how far each range's top sits above its bottom
US$205 is above the whole range from comparing PTC with listed peers (Synopsys, Cadence, Autodesk, Dassault Systèmes, Bentley, Nemetschek, and industrial groups including Siemens and Schneider itself), from typical takeover premiums, and from a discounted future share price. It falls inside the discounted-cash-flow range of US$160 to US$210 and the two ranges built from past industrial-software deals. Company X’s US$228 is the top of one of those, the deals priced on ARR.1
On premiums, Evercore found a median of 33% in selected all-cash deals and bids above US$10bn for US companies since 2016, and 31% in technology deals; Schneider’s is 42.3% over the last close and 46.1% over the 30-day volume-weighted average.12 Evercore’s fee is about US$120m, of which US$2m was paid when it gave its opinion and the rest is due only if the merger closes. The proxy also discloses that Evercore earned US$3m to US$7m in the past two years advising a company in which Schneider held a minority stake.1
Sources
- PTC Inc.: definitive merger proxy statement (Schedule 14A, DEFM14A) — 13 November 2026
- Schneider Electric and PTC: “Schneider Electric to acquire PTC” (PTC Form 8-K, Exhibit 99.1) — 5 October 2026
- PTC Inc.: fourth fiscal quarter and full fiscal year 2026 results (Form 8-K, Exhibit 99.1) — 4 November 2026
- PTC Inc.: Annual Report on Form 10-K for the fiscal year ended 30 September 2025 — 21 November 2025
- Nasdaq.com: PTC Inc. (PTC) historical prices — 13 November 2026 Daily closes, 1 July 2025 to 13 November 2026. Not a primary source.
Disclosure. TechBag is a software reseller: it earns when companies buy through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading