Heptamax, worth S$6.3m, agrees to buy data-centre operator Racks Central for S$500m
Heptamax’s SGX filing of 18 November: S$500m in new shares for an 8 MW Tai Seng data centre, a reverse takeover leaving the seller with 94.66%, and what must happen first.

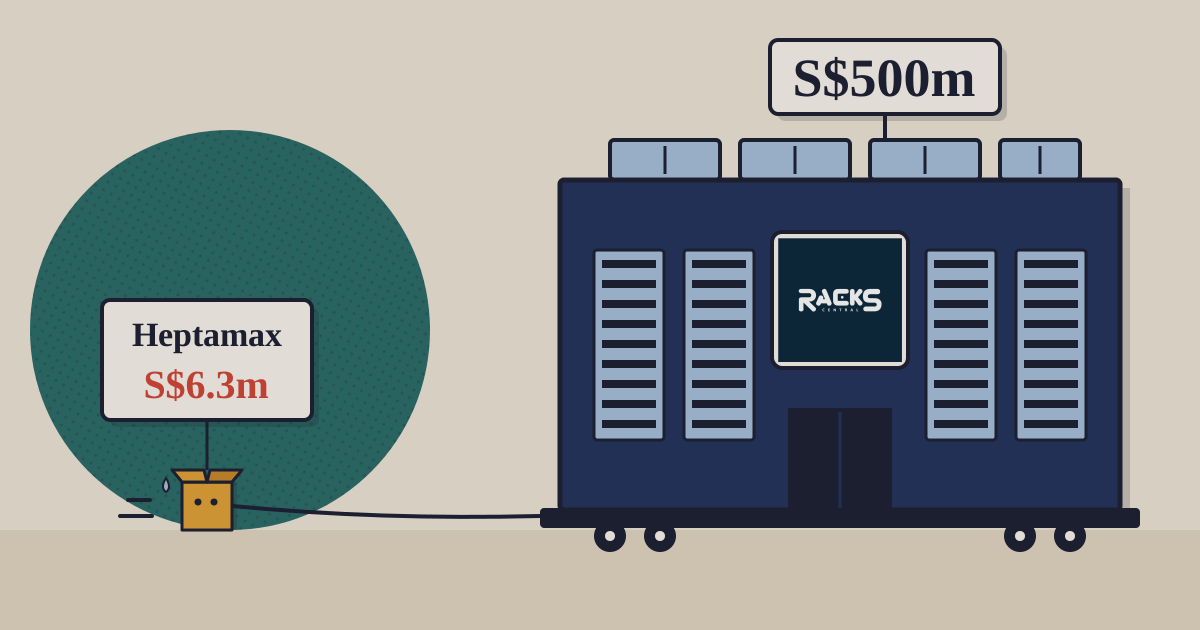
Heptamax International, a company on the Singapore Exchange’s Mainboard whose shares were worth S$6.28m, has agreed to buy Racks Central, which runs a data centre at Tai Seng in eastern Singapore, for S$500m paid entirely in new Heptamax shares, plus up to S$75m more if Racks Central’s earnings reach a target in 2027.1 If it completes, the seller would own about 94.66% of the enlarged company, to be renamed Racks Central Limited. The announcement, filed at 8:22pm on 18 November, says the deal “will result in a reverse takeover” under Chapter 10 of SGX’s listing rules.1
S$500m
initial price, all in new Heptamax shares at S$0.612 each
Heptamax, SGX
S$6.28m
Heptamax’s market value in the filing, at its 5 November price
Heptamax, SGX
94.66%
of the enlarged company the seller would own after completion
Heptamax, SGX
~8 MW
IT capacity of Racks Central’s Tier III data centre, open since 2014
Heptamax, SGX
01How a S$6m company pays S$500m
It pays in its own shares. Heptamax would first merge every two shares into one, then issue up to 816,993,464 new shares at S$0.612 to the seller, Racks Central Holdings, and further shares equal to 2.5% of the enlarged company to Assurance Dynamics, the arranger that introduced the two sides.1 The issue price equals S$0.306 on today’s shares, 2.4 times the S$0.128 at which the filing values them. That is what makes it a reverse takeover: the listed buyer ends up owned by the seller, and Racks Central gains a listing without an IPO.
Singapore’s Takeover Code requires anyone who crosses 30% to offer for all the other shares. The seller will instead ask the Securities Industry Council for a “whitewash waiver”, which Heptamax’s independent shareholders must also approve at a meeting. A later share placement would restore the minimum public float.1
02What Racks Central earns
Racks Central’s revenue rose from S$28.7m in 2023 to S$36.9m in 2025; pre-tax profit went from S$1.26m to S$1.45m. At the end of 2025 it had net assets of S$22.0m and liabilities of S$123.5m. The price was “calculated based on the EBITDA” for 2025, a figure the filing does not give. Unaudited management accounts put pre-tax profit at about S$18.8m for January–September 2026; the same filing gives S$2.29m for January–June, which leaves about S$16.5m for July–September. The extra S$75m is due if EBITDA reaches S$70m in 2027. Heptamax says it has not independently verified the seller’s figures.1
Heptamax lost S$1.2m in 2025 and had net tangible assets of S$55,000. Its remaining project, a robotic-dog surveillance and patrol system for one customer, is to be transferred out at completion, after which it would have no business but Racks Central.1
03What has to happen, and the Malaysian option
Completion needs an independent valuation of at least S$425m (a shortfall of up to S$75m comes off the earn-out first), due diligence within 60 business days, approval from SGX and from shareholders, and the waiver, by a long-stop date 15 months after signing, 18 February 2028, unless extended. Heptamax also gets an option to buy 10% of Racks Central (M) for S$25m in shares, a value of S$250m for the whole, exercisable only after that company is first paid by a data-centre customer, and first refusal on the seller’s other data-centre interests in Singapore, Malaysia and Indonesia.1
The shares barely trade. On Friday 24,000 changed hands at S$0.130–0.132, the first trades since 5 November, closing at S$0.131, up 2.3%. The S$0.128 the filing uses came from 1,900 shares worth S$243 on 5 November.2 What to watch: the shareholder circular, which will carry the independent valuation and the independent adviser’s view on the waiver.
Sources
- Heptamax International, “Proposed Acquisition of the Entire Issued and Paid-Up Share Capital of Racks Central Pte. Ltd.” (SGX announcement SG261118OTHR2ZJQ, broadcast 20:22 SGT) — 18 November 2026
- Singapore Exchange, Heptamax (8A1) daily prices and volumes, 22 October to 20 November 2026 — 20 November 2026
Disclosure. TechBag is a software reseller: it earns when companies buy through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading