SMIC’s revenue rose 33.9% to US$3.19bn; it guides its margin to 26–28% from 29.9%
SMIC’s results for July to September and its guide for the next quarter: why the margin rose, where the wafers went, how full its fabs ran, and what October to December is set to bring.

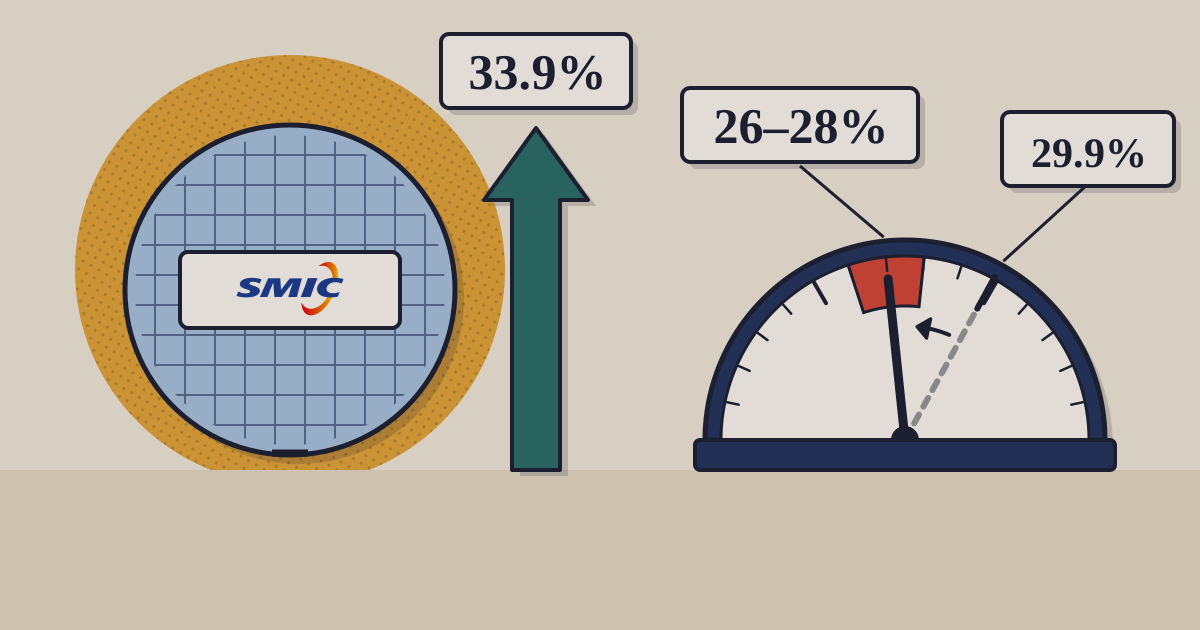
SMIC, the Shanghai chip foundry, made US$3.19bn of revenue in July–September, 33.9% more than a year earlier, and kept 29.9% of it as gross margin, up from 22.0%. Gross profit rose 82.3%, to US$953.2m.2 For October–December it guides revenue up 4% to 6% on the quarter and gross margin to 26–28%, below the quarter it has just reported.1 SMIC published the results on 12 November, after Hong Kong’s market had closed.2
US$3.19bn
revenue, July–September, up 33.9% on a year earlier
SMIC
29.9%
gross margin, from 25.3% in April–June and 22.0% a year earlier
SMIC
97.3%
of its capacity in use, from 93.7% in April–June
SMIC
26–28%
gross margin SMIC guides for October–December
SMIC
01Why the margin rose: full fabs
A foundry makes chips that other companies design, so much of its cost is the fabs themselves, written off as depreciation whether they run full or not: US$945.8m of SMIC’s US$2.24bn cost of sales in the quarter, 42%. Its total depreciation and amortisation reached US$1.27bn, up 27.6% on a year earlier.2 When more wafers go through the same fabs, that fixed cost is spread wider: SMIC shipped 3.03 million wafers (counted as 8-inch equivalents), 5.7% more than in April–June, and ran at 97.3% of capacity, against 93.7%. Revenue rose 6.1% on the quarter while cost of sales fell 0.4%. SMIC puts the margin gain down to the higher utilisation rate and a change in product mix.2 Monthly capacity grew to 1,116,750 8-inch-equivalent wafers, from 1,096,500.2
SMIC’s gross margin rose from 19.2% to 29.9% in three quarters as revenue passed US$3bn
Quarterly revenue (US$ million) and gross margin (%), October–December 2024 to July–September 2026
- Revenue (US$m)
- Gross margin (%)
Show tableHide table
| Revenue (US$m) | Gross margin (%) | |
|---|---|---|
| 4Q24 | 2,207.3 | 22.6 |
| 1Q25 | 2,247.2 | 22.5 |
| 2Q25 | 2,209.1 | 20.4 |
| 3Q25 | 2,381.8 | 22 |
| 4Q25 | 2,488.7 | 19.2 |
| 1Q26 | 2,505.5 | 20.1 |
| 2Q26 | 3,005.6 | 25.3 |
| 3Q26 | 3,190 | 29.9 |
Source: SMIC quarterly results releases, 10 February, 14 May, 13 August and 12 November 2026 · as of 12 November 2026 · each quarter as SMIC reported it; IFRS
The quarter beat SMIC’s own forecast. In August it guided revenue up 2% to 4% and gross margin to 26–28%;3 it delivered 6.1% and 29.9%.1 The quarter before went the same way: guided in May to a 20–22% margin,5 SMIC reported 25.3%.3 For TSMC, the largest foundry, monthly sales are in our Trend on its October record.
02Where the wafers go
China accounted for 90.8% of SMIC’s revenue, up from 86.2% a year earlier; America’s share fell to 7.8% from 10.8%. By what the chips go into, smartphones fell to 14.3% of wafer revenue from 21.5%, while industrial and automotive rose to 19.3% from 11.9%, and computers and tablets to 18.3% from 15.2%. Consumer electronics stayed the largest group, at 40.6%. Twelve-inch wafers made up 78.9% of wafer revenue.2
03Profit, cash and what to watch
Profit attributable to SMIC’s shareholders was US$428.4m, 123.4% more than a year earlier but 10.6% less than in April–June, when gains on investments held through associates added US$275.9m of other income; this quarter that line was a US$32.1m loss.2 Capital spending was US$1.09bn, against US$1.84bn in April–June. Borrowings rose to US$14.9bn, against US$13.4bn of cash and deposits.2
The release does not say why the margin guide is lower, and the filing gives no split by process node. SMIC holds its call on 13 November.1 In February it guided 2026 revenue growth above the industry average in its markets, with capital spending roughly flat on 2025.4
Sources
- SMIC: SMIC reports 2026 third quarter results (press release) — 12 November 2026
- SMIC: SMIC reports unaudited results for the three months ended September 30, 2026 (HKEX announcement, stock code 00981) — 12 November 2026
- SMIC: SMIC reports 2026 second quarter results (press release) — 13 August 2026
- SMIC: SMIC reports 2025 fourth quarter results (press release) — 10 February 2026
- SMIC: SMIC reports 2026 first quarter results (press release) — 14 May 2026
Disclosure. TechBag is a software reseller: it earns when companies buy through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading